Person
An account holder must understand the amount, date, reason, right, and action before the financial consequence advances.
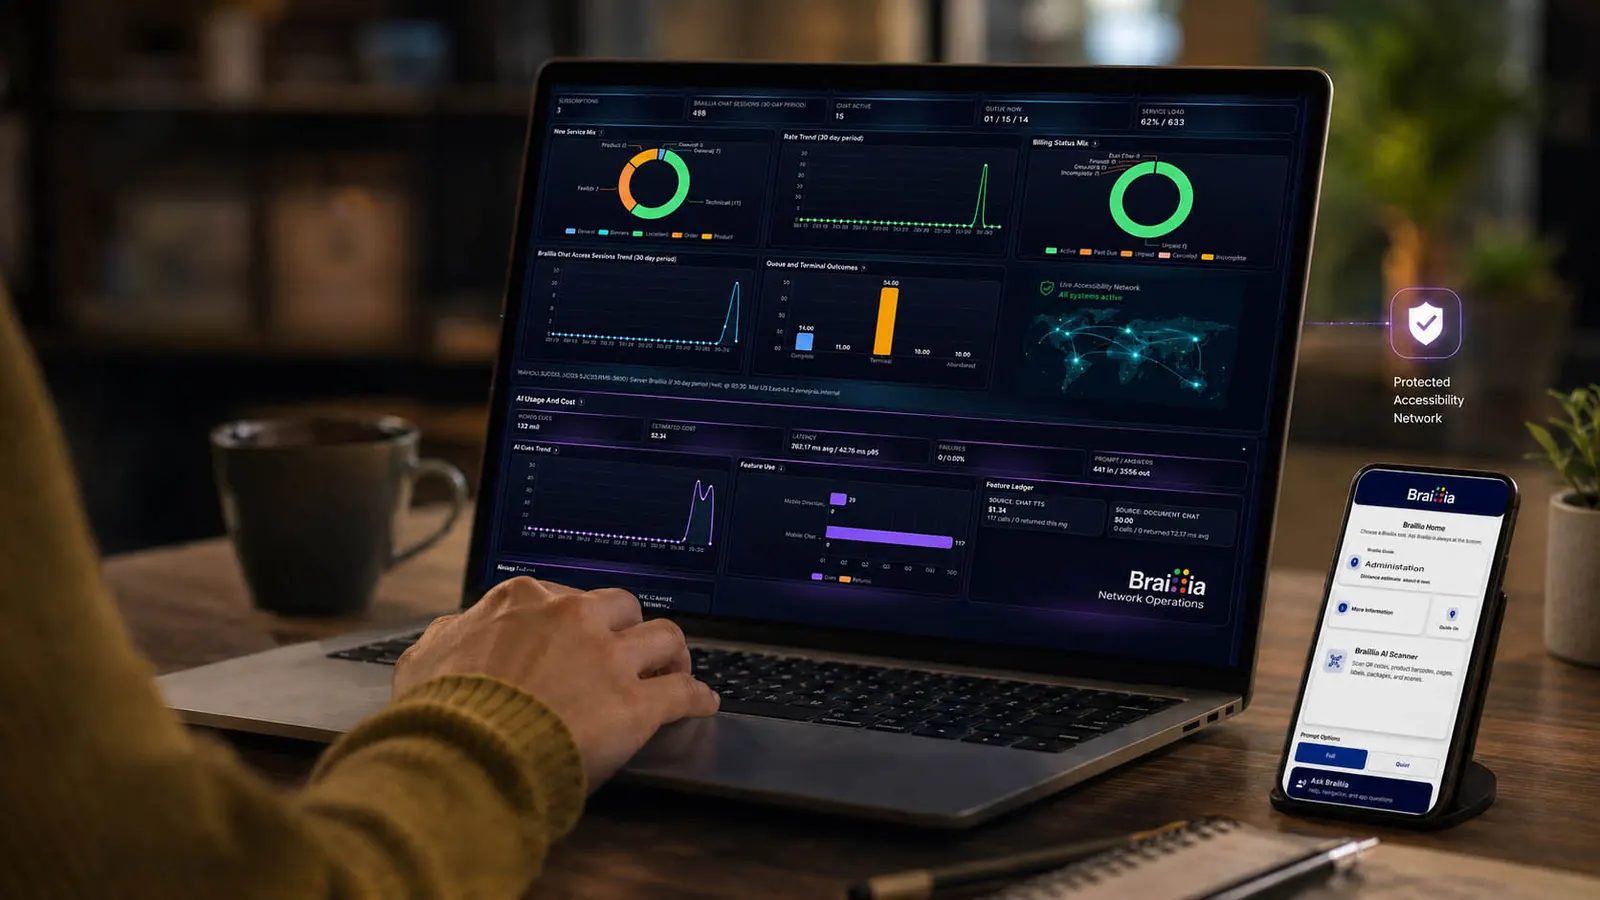
Braillia network operations interface connecting enterprise processing, protected accessibility services, and a mobile experience.
Financial communication accessibility
Braillia helps financial institutions, communications teams, and technology providers transform statements, adverse-action notices, fraud alerts, fee and collections communication, disclosures, and account notices into structured, accessible information customers can use independently.
Person
An account holder must understand the amount, date, reason, right, and action before the financial consequence advances.
Control
The organization owns the outcome; its platform or provider may control the technology.
First move
Choose one consequential workflow, identify its owner, and prove a usable path.
The access consequence
A statement, fraud alert, adverse-action notice, fee disclosure, collections communication, or account change can require a fast and informed response. If the information isn't independently usable, the customer may miss a dispute window, payment, correction, protection step, or decision that affects their money and trust.
A customer can miss the amount, due date, transaction detail, fee reason, or action required to keep the account current.
An inaccessible notice can delay recognition, reporting, identity protection, a dispute, or a response while financial exposure continues.
A customer can miss the reason, right, disclosure, deadline, or next step connected to a consequential financial decision.
The information chain
Accessibility can fail at several points, but a credible implementation begins where the responsible organization or its provider can actually change the information path.
Core banking, lending, card, collections, fraud, customer, and account data
Statement, document-composition, customer communications, and archive platforms
Digital banking, portal, email, PDF, print, branch, and support channels
An account holder who must independently understand and act on the information
Pay, dispute, verify, respond, protect an account, or understand a decision
Enter where change is possible
Braillia can work directly with the organization where it owns the information, or through the provider and integrator where the platform controls production and delivery.
Institution-sponsored entry
A community or regional institution can sponsor a focused statement, fraud, adverse-action, fee, collections, disclosure, or account workflow. That evaluation establishes the customer need and production boundary before a broader provider integration decision.
Primary control
Braillia's role
Transform an authorized representative communication into appropriate accessible outputs, preserve the financial facts and required actions, and document where the institution and its providers control the path.
Provider-led entry
When core banking, digital banking, statement, customer communications, archive, or portal technology controls recurring output, the provider or implementation partner becomes the practical route to scale across institutions.
Primary control
Braillia's role
Define a source-specific transformation and validation path that returns accessible information to the institution's existing delivery workflow without replacing the system of record.
The credible first workflow
Choose a recurring or time-sensitive communication with a clear owner and customer action. The evaluation should prove whether the account holder can locate the amount, date, reason, right, and next step without staff reading the document for them.
Review a Financial CommunicationThe approval team
Where are customers abandoning, delaying, or requesting staff to interpret account information?
Which statement or notice has a clear owner, action, and recurring production path?
What customer outcome, standard, and review evidence must the institution establish?
Which systems, financial data, access, retention, and integration boundaries apply?
Where can accessible output enter the recurring production and delivery workflow?
Evidence for the decision
Give accessibility, operations, IT, security, and procurement the evidence they need before the first implementation decision.
Review current Braillia intake, processing, output, and remediation states.
Open Evidence PackageSee how a source-specific implementation can fit around an existing core, statement, archive, or communications system.
Review IntegrationPrepare data-handling, access, retention, and implementation questions for a controlled financial workflow.
Review SecurityDefine the communication, owners, outputs, evidence, and scale decision before implementation begins.
Open Scope TemplateBuyer questions
Government and business teams can begin with one accountable workstream, then expand the operating model only when another accessibility responsibility requires it.
Braillia works around existing systems. An institution can sponsor one consequential communication, then include its core, statement, digital, or communications provider where that provider controls recurring production and delivery.
Begin with one statement, fraud notice, adverse-action communication, fee or collections notice, disclosure, or account change with a named owner and measurable customer outcome.
No. Each implementation begins by confirming the source, schema, production workflow, security boundary, outputs, and responsible provider. Braillia then scopes the integration required for that environment.
Bring Braillia one statement, fraud, adverse-action, fee, collections, disclosure, or account communication. We'll define who controls it, what the person must accomplish, what evidence matters, and where Braillia can enter.